Management Consulting in the Age of AI
Management consulting is being repriced, and the industry that spent a century warning other businesses about disruption is now the one being disrupted. The mechanism is not that AI writes better strategy than a good partner. It is that AI has made cheap the specific thing consulting has always sold at a premium: the hours of skilled analysis that turned a question into a deck. When the input gets commoditised, the model built to sell that input by the hour gets repriced with it. That is the story of consulting in the age of AI, and it is already underway.
This is not a prediction about robots replacing strategists. It is an observation about a business model. The consulting industry runs on billable hours and a leverage pyramid: partners sell the engagement, and armies of junior analysts do the research, modelling, and documentation that fill the hours. AI is strongest at exactly that junior-analyst layer. When the layer that generated the billable hours can be done in minutes, the economics that the whole pyramid rested on stop adding up.
The model under pressure
The traditional consulting model was built on billable hours, projects, and static deliverables, and that model is rapidly losing relevance. Clients who once paid premium rates for expertise are now asking a sharper question: why pay for hours of work that our own team, armed with the same tools, can do in an afternoon?
Clayton Christensen named this dynamic in *The Innovator’s Dilemma*: incumbents get overtaken not because they are lazy but because the ground under their business model shifts, and the very thing that made them profitable makes them slow to adapt. Consulting is a near-perfect case. The billable-hour model is not a detail the firms can quietly swap out. It is the foundation the partnership, the promotion track, and the profit share are all built on. Changing it means changing what the firm is.
The evidence is already visible inside the largest firms. The Big Four have slowed partner promotions, and the reason cited is AI uncertainty: partnerships are decided on whether a candidate can generate a decade or more of future revenue, and with AI compressing the research, modelling, and documentation that leverage depends on, firms can no longer forecast how much human work will stay billable. When an industry stops promoting because it cannot predict its own future revenue, the disruption is not coming. It has arrived.
What AI actually commoditises
Be precise about what is being repriced, because the imprecise version (“AI will replace consultants”) is both wrong and useless.
AI commoditises the input. The literature review, the market sizing, the first-draft financial model, the competitive scan, the synthesis of a hundred documents into a summary: this is the work that used to require a room of analysts and a fortnight, and it is the work a capable team can now do in an afternoon. The specialised knowledge that justified the premium, the fact that the consultant had read the reports and built the models you had not, is now available to anyone with a subscription. That asymmetry was a large part of what you were paying for, and it is gone.
This is why the leverage pyramid is the part under the most strain. The pyramid monetised the gap between what a partner knew and what a client could produce. AI narrows that gap for the routine analytical work faster than anywhere else in the business.
What it does not commoditise
Now the other half, because it is the half that matters for anyone deciding what to buy or build.
AI does not commoditise judgment: knowing which question is the real one, which analysis is load-bearing and which is theater, and what to actually do when the model and the politics disagree. It does not commoditise accountability: someone who owns the outcome and answers for it when it is wrong, which no tool and no first-draft can do. And it does not commoditise proprietary assets: the data, the domain knowledge, the methods, and the relationships that a specific firm has and a general-purpose model does not.
This is where the industry’s own analysts expect the value to migrate. As efficiency becomes table stakes, the firms that hold up are the ones that compete on differentiation through proprietary assets, data, brand, domain knowledge, and outcomes, rather than on the hours it takes to produce a deliverable. The durable layer is judgment and ownership. The commoditised layer is the hours. Consulting is being split down that seam.
From selling hours to owning outcomes
The pricing model follows the value, and it is already moving. When the cost of inputs collapses, charging for inputs stops making sense, so the industry is shifting towards pricing based on outcomes, results, and the quality of what is delivered rather than the time it took. You see it in the legal world’s slow renegotiation of the billable hour and in consulting’s growing experiments with results-based and success-based fees.
The logic is simple once the input is cheap. A client will not pay for the hours it took to produce a recommendation they could have produced themselves. They will pay for a result they could not have reached alone, and for someone who owns that result with them. That is a different business, and it rewards a different kind of firm: one built to own outcomes rather than to bill time.
None of this shrinks the market. The AI consulting market is projected to grow from roughly $11 billion in 2025 to nearly $91 billion by 2035, and the largest firms are booking AI revenue in the billions (Future Market Insights, 2025). The money is not leaving. It is shifting off billable hours and onto owned outcomes and proprietary assets.
What this means if you buy consulting
For anyone deciding how to buy help in this market, the shift changes the question. The old question was “which firm has the best people to rent for this project?” The better question now is “who will own the outcome with me, and what do I keep when the engagement ends?”
Stop paying premium rates for analysis your own team can now do with the same tools. Do pay for the two things AI cannot give you: judgment on the decisions that compound, and an owned system you keep. If an engagement leaves you with a deck and no owned capability, you have rented expertise at a moment when expertise is getting cheap. If it leaves you with a working system, a documented operating model, and someone who owned the result, you have bought the part that still holds its value. It is the difference between renting expertise you can now get cheaply and owning a stack that stays portable.
This is the frame Thane Alaric was built on: not a firm that sells you hours of AI expertise, but one that builds what your business needs and stays responsible for it working, while your team owns what gets built. The industry is being repriced around ownership. The firms that win the next decade, the ones you hire and the ones you become, are the ones that own what they build rather than bill for the time it took.
The question to put to your own firm is narrower than it looks: how much of next year’s growth still depends on expertise you rent, and how much of it runs on something you already own.
If the repricing is real, the useful response is to own a system rather than buy another opinion about one: tell Daniel what your business runs on today, what you have already built, and what you need it to do. Book 30 minutes with Daniel.
Frequently Asked Questions
Will AI replace management consultants?
Not wholesale, but it is replacing a large part of what consultants used to sell: the research, modelling, and first-draft analysis that filled billable hours. What AI does not replace is judgment on which decisions matter, accountability for outcomes, and proprietary assets a general model does not have. Consultants who own outcomes will do well; those who rent out hours of routine analysis will be repriced.
How is AI changing management consulting?
AI is commoditising the analytical input the industry’s leverage model was built to sell, which puts the billable-hour and junior-analyst pyramid under pressure. The value is migrating to judgment, owned outcomes, and proprietary assets, and pricing is shifting from hours towards results. The largest firms are already slowing promotions because they cannot forecast how much human work will remain billable.
What happens to the billable-hour model in consulting?
It is being repriced rather than abolished overnight. When the inputs that generated billable hours become cheap, charging for those inputs stops making sense, so firms are moving towards outcome-based, success-based, and quality-based pricing. The billable hour will likely persist at the edges, but it is no longer a safe foundation for a firm’s economics.
Should companies still hire management consultants?
Yes, but for different reasons than before. Stop paying premium rates for analysis your own team can now produce with the same tools. Pay for judgment on decisions that compound and for an owned system you keep after the engagement ends. The test is what you retain: a deck is rented expertise, while a working system and a documented operating model are owned capability.
What is the future of consulting firms?
The market is growing, projected from around $11 billion in 2025 to nearly $91 billion by 2035, but the money is moving from hours to outcomes and from generic analysis to proprietary assets. Firms built to own outcomes and to leave clients with durable capability will capture that growth; firms built purely on billable leverage face the innovator’s dilemma in full.
How should firms buy AI and consulting help in this market?
Ask who owns the outcome and what you keep when the work ends. Rent commodity capability, models and generic tools, cheaply and stay ready to switch. Buy, and own, the judgment and the operating model that create durable advantage. The worst outcome is paying premium rates to rent expertise that is getting cheaper while keeping nothing you can build on.
About the Author
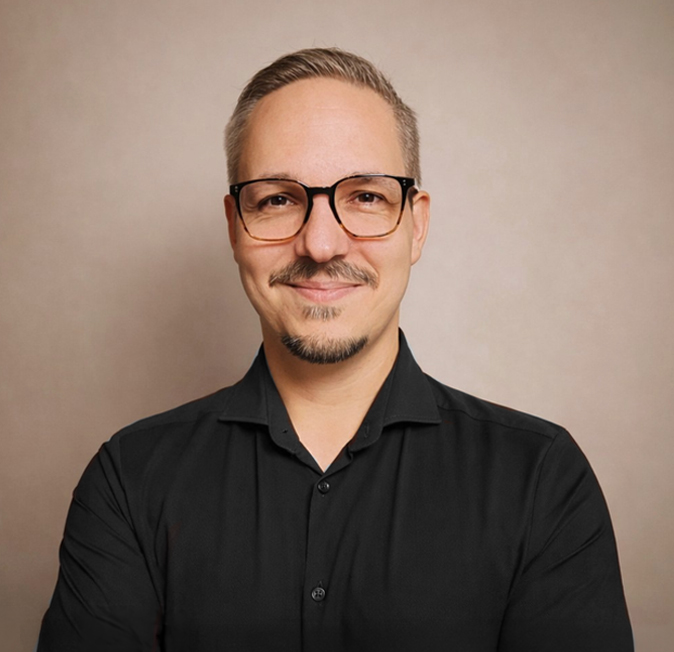
Daniel Förster is the Managing Partner of Thane Alaric. He has built nine businesses, delivered dozens of projects and worked with more than 2,000 founders, across AI and technical systems of every kind, funnels, marketing, sales and leadership. He works owner to owner, and Thane Alaric runs on the same systems it builds. Business-to-Life. We build the business your vision needs.